Official primary source
- Effective from
- Verified
- Review by
Give your goal a place in your monthly budget.
Start with the money set aside for this goal. Compare the monthly amount you need with the time your current plan takes.
Monthly amount needed by your date
1,670,000 KRW
Calculation in whole KRW: 1,666,667 KRW / mo
Add KRW 100,000 each month7yr 7mo
Allow one more year1,390,000 KRW
| mo | Contributions | Balance after fees | After assumed tax | Comparable balance |
|---|---|---|---|---|
| 0 | 0 KRW | 0 KRW | 0 KRW | 0 KRW |
| 5 | 5,000,000 KRW | 5,000,000 KRW | 5,000,000 KRW | 5,000,000 KRW |
| 10 | 10,000,000 KRW | 10,000,000 KRW | 10,000,000 KRW | 10,000,000 KRW |
| 15 | 15,000,000 KRW | 15,000,000 KRW | 15,000,000 KRW | 15,000,000 KRW |
| 20 | 20,000,000 KRW | 20,000,000 KRW | 20,000,000 KRW | 20,000,000 KRW |
| 25 | 25,000,000 KRW | 25,000,000 KRW | 25,000,000 KRW | 25,000,000 KRW |
| 30 | 30,000,000 KRW | 30,000,000 KRW | 30,000,000 KRW | 30,000,000 KRW |
| 35 | 35,000,000 KRW | 35,000,000 KRW | 35,000,000 KRW | 35,000,000 KRW |
| 40 | 40,000,000 KRW | 40,000,000 KRW | 40,000,000 KRW | 40,000,000 KRW |
| 45 | 45,000,000 KRW | 45,000,000 KRW | 45,000,000 KRW | 45,000,000 KRW |
| 50 | 50,000,000 KRW | 50,000,000 KRW | 50,000,000 KRW | 50,000,000 KRW |
| 55 | 55,000,000 KRW | 55,000,000 KRW | 55,000,000 KRW | 55,000,000 KRW |
| 60 | 60,000,000 KRW | 60,000,000 KRW | 60,000,000 KRW | 60,000,000 KRW |
Financial assets · deposits at month start · annual input/12 monthly rate. Fees reduce the annual return assumption. Simple tax is applied only to positive gains at each observation date. This is not a product- or account-specific tax calculation. Purchasing-power mode also adjusts for inflation.
The headline monthly amount is rounded up to KRW 10,000. Calculations use whole-KRW values.
Only the Save button stores your inputs in this browser. Inputs are not sent to a server or shared URL.
Subtract living costs and reserves from take-home pay. Leave out one-off benefits and refunds you have not received.
Monthly savings capacity0 KRW
global-goal-savings-v1Savings-goal simulation in Korean won (KRW).
Official primary source
Official primary source
How much must I save each month to reach my target on time?
B_m = (B_(m-1) + C) × (1 + (r − f) / 1200); A_m = B_m − max(B_m − P_m, 0) × t / 100; R_m = A_m / (1 + i / 100)^(m / 12)
| Item | Value | Definition and units |
|---|---|---|
B_m | Balance after fees | Month-end balance after this month’s contribution and return, in KRW. |
B_(m-1) | Balance after fees | Previous month-end balance; starting capital is used for the first month. |
C | Monthly contribution | The same contribution added at each month’s beginning, in KRW. |
r | Assumed annual return (%) | User-entered nominal annual return, in percentage points. |
f | Annual fee assumption (%) | Assumed annual fee deducted from annual returns, in percentage points. |
A_m | After assumed tax | Balance after hypothetical tax on positive cumulative gains at the observation date, in KRW. |
P_m | Contributions | Starting capital plus all contributions through the current month, in KRW. |
t | Tax assumption on positive gains (%) | Simple tax assumption on positive cumulative gains, in percentage points. |
R_m | Today’s purchasing power | After-assumption-tax balance expressed in today’s purchasing power, in KRW. |
i | Annual inflation assumption (%) | Assumed annual inflation used to adjust purchasing power, in percentage points. |
m | Months until the target date | Whole months elapsed since the starting date. |
Start at zero, contribute KRW 1 million monthly, and target KRW 100 million in 60 months. All rates are 0%; the target is nominal.
| Item | Value |
|---|---|
| Money already set aside | 0 KRW |
| Monthly contribution | 1,000,000 KRW |
| Target amount | 100,000,000 KRW |
| Months until the target date | 60 months |
| Assumed annual return (%) | 0% |
| Annual fee assumption (%) | 0% |
| Tax assumption on positive gains (%) | 0% |
| Annual inflation assumption (%) | 0% |
| What the target amount means | Future account balance |
| Item | Value |
|---|---|
| Monthly amount needed by your date | 1,666,667 KRW |
| Time at your current contribution | 100 months |
| Comparable balance at the deadline | 60,000,000 KRW |
The current contribution reaches the target in 100 months. Meeting 60 months requires KRW 1,666,667 each month. Check whether your budget can cover the gap before changing return assumptions.
Start with KRW 20 million and contribute KRW 1.1 million monthly toward KRW 100 million in 60 months. All rates are 0%.
| Item | Value |
|---|---|
| Money already set aside | 20,000,000 KRW |
| Monthly contribution | 1,100,000 KRW |
| Target amount | 100,000,000 KRW |
| Months until the target date | 60 months |
| Assumed annual return (%) | 0% |
| Annual fee assumption (%) | 0% |
| Tax assumption on positive gains (%) | 0% |
| Annual inflation assumption (%) | 0% |
| What the target amount means | Future account balance |
| Item | Value |
|---|---|
| Monthly amount needed by your date | 1,333,334 KRW |
| Time at your current contribution | 73 months |
| Comparable balance at the deadline | 86,000,000 KRW |
The current contribution reaches the target in month 73. A 60-month deadline needs KRW 1,333,334 monthly. Account for both existing money and future contributions.
Compare arrival times when monthly contributions increase.
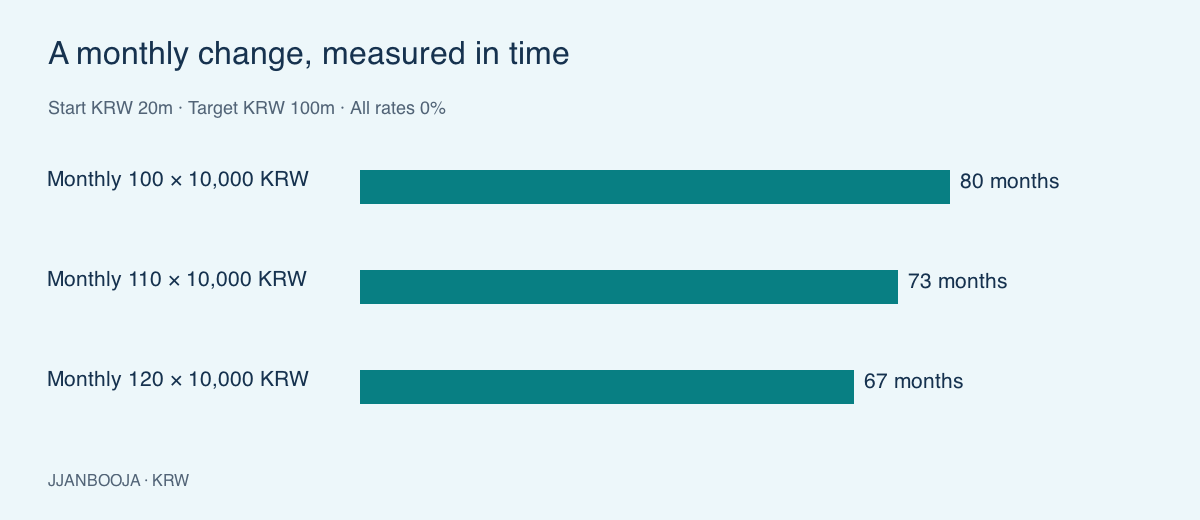
With KRW 20 million initially, a KRW 100 million target and all rates at zero, monthly contributions of KRW 1m, 1.1m and 1.2m reach the target in 80, 73 and 67 months.
Three inputs differing only in monthly contributions use the same goal engine. Bar lengths are proportional to arrival months.
Start at zero, target KRW 100 million in 60 months, contribute KRW 1 million monthly, and assume 5% annual returns. Only fees change; tax and inflation are zero.
| Condition | Monthly amount needed by your date (KRW) | Time at your current contribution (months) |
|---|---|---|
| 0% annual fees | 1,464,356 KRW | 7yr |
| 1% annual fees | 1,503,308 KRW | 7yr 3mo |
The 5% return is an illustration. Check product-specific fees and taxation separately.
Start at zero with a KRW 100 million target and KRW 1 million monthly contributions. All rates are zero; only the deadline changes.
| Condition | Monthly amount needed by your date (KRW) | Time at your current contribution (months) |
|---|---|---|
| 60-month deadline | 1,666,667 KRW | 8yr 4mo |
| 72-month deadline | 1,388,889 KRW | 8yr 4mo |
Arrival depends on current contributions, so changing the deadline does not change arrival. It changes the required monthly contribution.
Start at zero, target KRW 100 million in 60 months, and set all rates to zero. Only the actual monthly contribution changes.
| Condition | Monthly amount needed by your date (KRW) | Time at your current contribution (months) |
|---|---|---|
| KRW 1.1m monthly | 1,666,667 KRW | 7yr 7mo |
| KRW 1.2m monthly | 1,666,667 KRW | 7yr |
The required contribution uses the same 60-month deadline. Increasing actual contributions shortens arrival time.
The headline rounds up to KRW 10,000 for a practical monthly budget. The exact minimum whole-KRW amount appears directly below.
It is a target for the savings balance entered here. Outstanding debt is not deducted automatically. Subtract debt service in the budget and track debt separately for a net-worth goal.
Calculations run in this page. Only a plan you explicitly save remains in this browser. Income and expense entries from the budget are not saved.